Tag Archives: IRAs

TikTok Tax Advice

There’s tax advice available on TikTok. Is it worth following? Does it miss the big picture?

Retirement Saving Through Various Forms of Life Insurance

TikTok tax advice often boils down to something like the following: don’t save in traditional retirement accounts where you will get crushed by taxes in retirement. Rather, save for retirement through permanent life insurance products (such as indexed universal life insurance policies) to get tax free growth and tax free withdrawals during retirement. 

Watch me discuss two problems with TikTok tax advice on YouTube.

This advice is not just offered on TikTok, though, anecdotally, it appears TikTok is at least something of a hub for promoting indexed universal life (“IUL”) and other forms of permanent life insurance. 

One recent example of this sort of advice posits a retired couple making $160,000 a year in IRA/401(k) distributions and $40K in Social Security/pension income and worries that the couple will have a terrible tax problem. 

But is that really the case? Let’s play it out with a detailed example.

Sally and Joe both turn age 75 in 2022. They are California residents. During their working years, they were prodigious savers in their workplace 401(k) plans, and their employers offered generous matching contributions. As a result, in 2022 they have required minimum distributions (“RMDs”) of $160,000. They also will have $40,000 of Social Security income, $4,000 of qualified dividend income, and $1,000 of interest income. Further, being tax savvy, they contribute $500 a month to their church through qualified charitable distributions (“QCDs”) from their traditional IRAs. They claim the standard deduction as their home is paid off and thus have no mortgage interest deductions. 

Alright, let’s see what Sally and Joe’s 2022 tax picture (all numbers are estimates) looks like:

First, their rough 2022 federal income tax return:

Federal Income Tax Return
RMDs$ 160,000
Social Security$ 40,000
15% Social Security Exclusion$ (6,000)
Interest$ 1,000
Qualified Dividends$ 4,000
QCD RMD Exclusion$ (6,000)
Adjusted Gross Income (“AGI”)$ 193,000
Standard Deduction$ (25,900)
Additional SD Age 65+$ (2,800)
Federal Taxable Income$ 164,300

Let’s turn to what their $164,300 federal taxable income means in terms of federal and California income taxes paid and their 2022 cash flow:

2022 Income Taxes and Cash Flow (Estimated)
Federal Income Tax$ 27,100
Effective Tax Rate on AGI14.04%
Marginal Federal Income Tax Rate22%
California Taxable Income (Approximate):$ 149,000
California Income Tax (Approx.)$ 7,862
Effective CA Income Tax Rate on Fed AGI4.07%
Marginal CA Income Tax Rate9.30%
Total Fed & CA Effective Income Tax Rate18.11%
Cash Flow After Fed & CA Income Tax & QCDs$ 164,038

By my math, after paying both income taxes and charitable contributions, this retired couple has $164,000 in cash flow for living expenses. Considering that, like many retirees, they live in a paid-off home, do we really believe there is a significant risk they will not be able to pay their bills? This couple ought to be able to enjoy a very pleasant, comfortable lifestyle, including recreational activities and travel.

Are Sally and Joe really getting crushed by income taxes? As residents of a high tax state, they do pay about $35K in combined federal and state income taxes. Sure, if $35K was on the table in front of you, you’d grab it pretty quick. But considering the $200K plus in cash flow they generated during the year, paying $35K in income taxes to the IRS and California is hardly financially debilitating. 

Most retired couples, even financially successful couples, will not have federal adjusted gross income of $193,000. If Sally and Joe are not crushed by income taxes (paying just an 18.11% estimated effective rate even living in a high-tax state), it is likely most retirees will be able to withstand the tax hits at retirement from having significant savings in traditional deferred retirement accounts. 

The Trade-Off Unstated on TikTok

TikTok tax advice often presents the boogeyman of taxes in retirement. It says “don’t invest in your 401(k) because it will get crushed in retirement.” Even if that were true, it usually neglects an important consideration: the upfront benefit of investing in a 401(k). 

During their working careers, it is likely that Joe and Sally were subject to marginal income tax rates of 24% or more federal and 9.3% California. Had they used permanent life insurance to save instead of using their 401(k)s, they would have lost 33 cents (or more) on every dollar in immediate tax savings, as there is no tax deduction for amounts contributed to life insurance policies.

The existence of the tax deduction for amounts contributed to a traditional 401(k) does not automatically mean that using permanent life insurance products for retirement is a bad idea. However, in weighing the tax benefits of the traditional 401(k) approach compared to the permanent life insurance approach, one must consider the immediate, and potentially substantial, tax benefits of traditional 401(k) contributions. 

One consideration in weighing the pros and cons of each: traditional 401(k) contributions generally get a tax benefit at the taxpayer’s marginal tax rate, while withdrawals from traditional 401(k)s and IRAs are more generally taxed at a taxpayer’s lower effective rate. On the way out, withdrawals are taxed through the relatively progressive tax brackets existing today, getting the benefits of the 10%, 12%, and 22% federal income tax brackets. 

Uncertainty

But, Sean, what about future tax rate increases! The federal government is running a huge deficit and it’s not getting any better.

This is a valid point. But let’s consider a few things. First, in my example, Sally and Joe were subject to a 33.3% marginal tax rate during their working years, and barely over an 18% effective tax rate during their retirement. For the math to work out to make permanent life insurance more attractive (tax-wise) than traditional 401(k)s for them, tax rates would need to be increased substantially, by over 80%. Thus, even if tax rates on retirees such as Joe and Sally were to increase 85% from current levels, the tax math might only marginally favor using permanent life insurance instead of a traditional 401(k). 

Second, if there are going to be income tax rate increases, they are more likely to be to the upper tax brackets. There are fewer taxpayers (read: voters) subject to the higher tax brackets, so those are the ones the politicians are more likely to increase. Increasing the 10%, the 12%, and/or the 22% tax brackets will impact more voters and lead to more election risk for the politicians.

Third, recent history suggests that the politicians are not likely to target retirees. It’s true that Social Security went from being tax free to being largely subject to taxation, up to 85% taxable. Interestingly enough, the second Social Security tax increase, which subjected Social Security to possibly being 85% taxable, passed through a Democratic Congress in 1993. The following year the Democrats suffered historic losses in the House and Senate elections. Many factors came into play, but it is interesting that since 1994 tax policy has generally benefited retirees (no more tax increases on Social Security, increasingly progressive tax brackets, and the increased standard deduction). 

Perhaps the politicians in both parties have learned a lesson when it comes to retiree taxation.

Is there zero risk that retirees could be subject to higher taxes in the future? Absolutely not. But, is that risk great enough to eschew traditional 401(k) contributions in favor of permanent life insurance? Not in my opinion.

Further, there are simpler, less costly planning techniques other than permanent life insurance that those using 401(k)s for retirement planning can avail themselves of, including Roth accounts and health savings accounts. 

Roth Accounts

Savers worried about future tax rate hikes have a simple, easy to implement tool to hedge against future tax rate increases: the Roth IRA. The Roth IRA solves the same tax problem that permanent life insurance solves for. In today’s environment, Roth IRAs are available at a vast array of financial institutions with very low fees. 

As I have previously discussed, many savers will benefit from the combination of a maxed out traditional 401(k) and a maxed out annual Roth IRA. 

Many will point out the possibility of much greater contributions to an indexed universal life insurance policy than to a Roth IRA. While true, many of those concerned with getting large amounts into tax-free accounts while working can turn to the Roth 401(k), which has significantly greater annual contribution limits than the Roth IRA. 

Roth Conversions

Many in the FIRE community have access to Roth conversions during what are likely to lower taxable income years. The tax idea behind retiring early is to load up on traditional 401(k) contributions during working years, and then convert amounts inside traditional retirement accounts to Roth accounts during early retirement years prior to collecting Social Security. 

In early retirement years, many in the FIRE movement appear, at least initially, to be poor on their tax return. No longer working, and not yet collecting Social Security, one’s tax return only includes interest income, dividend income, and some capital gains income. If that income is relatively low (which it is likely to be for many early retirees), it likely leaves room for Roth conversions at the 10% or 12% tax brackets during early retirement. 

This is tax rate arbitrage. First, deduct 401(k) contributions in the 24% or greater federal income tax brackets during one’s working years. Then, during early retirement, convert amounts in the traditional retirement accounts at a 10%, 12%, or perhaps 22% marginal federal income tax rate. 

Two observations: A) using permanent life insurance instead of traditional 401(k) contributions followed by early retirement Roth conversions denies members of the FIRE community a significant tax rate arbitrage opportunity. While there is no taxable income inclusion when withdrawing from a permanent life insurance policy, there is also no tax deduction for contributions to IULs, whole life insurance, and other permanent life insurance policies. 

B) By doing Roth conversions during early retirement, FIRE members reduce the uncertainty risk described above. FIRE members face a shorter time frame during which significant savings are in traditional retirement accounts, as the goal is (generally speaking) to get the money (mostly) converted to Roths prior to age 70.

The Roth conversion tool reduces the risk that future tax increases will crush savers who mostly use traditional 401(k)s during their working years. While this is true for all savers, it is most especially true for members of the FIRE community. 

A note on tax optimization: Imagine Joe and Sally were retired at age 55, today’s tax laws existed, and they had many years with artificially low taxable income. Say they did not do Roth conversions during this time. Is that a mistake? From a tax optimization perspective, absolutely. They would have likely been able to do Roth conversions at a 10% or 12% federal income tax rate, which is lower than both their retirement 22% marginal federal income tax rate and 18.11% combined effective income tax rate. While they are not tax optimized, they are something more important in my example: financially successful. Yes, tax optimization is important, but it is not the be-all and end-all. My guess is that financially successful individuals do not regret the failure to tax optimize on their deathbeds, though I look forward to reading Jordan “Doc G” Grumet’s new book to be sure. 

Conclusion

I’m not here to tell you exactly how to save for retirement. But I am concerned that TikTok tax advice has two deficiencies. First, it overstates the problem of taxation in retirement. Is there a potential problem? Yes. Is it as severe as some make it out to be? Not under today’s laws. Further, there are tactics such as annual Roth IRA contributions and Roth conversions during early retirement that can address the problem. Second, TikTok tax advice understates the current benefit of deductible traditional 401(k) contributions during one’s working years. 

Further Reading

Forbes has recently published two articles on the sorts of insurance policies frequently promoted on TikTok. They are available here and here. 

FI Tax Guy can be your financial planner! Find out more by visiting mullaneyfinancial.com

Follow me on Twitter at @SeanMoneyandTax

This post is for entertainment and educational purposes only. It does not constitute accounting, financial, legal, or tax advice. Please consult with your advisor(s) regarding your personal accounting, financial, legal, and tax matters. Please also refer to the Disclaimer & Warning section found here.

The Mystery of the Disappearing Tax Basis

Tax loss harvesting is all the rage in a down stock market. Did you know that it can create a mystery worthy of the Hardy Boys? Read on to find out how tax basis can disappear because of tax loss harvesting and the wash sale rule. 

Tax Loss Harvesting

I’ve previously written about tax loss harvesting. The idea is to sell a stock, bond, mutual fund, ETF, or other asset at a loss and report that loss on a tax return. That loss can offset other capital gains, and after having done that, it can offset ordinary income (W-2 income, interest income, etc.) up to $3,000 per year. Unused capital losses can be carried forward to subsequent tax returns indefinitely.

Tax loss harvesting is a nice tactic and in the right circumstances can be beneficial. That said, tax loss harvesting should not be a primary driver of one’s investment portfolio allocation. 

The Wash Sale Rule

The opportunity presented by tax loss harvesting has a major hurdle: the wash sale rule. Any acquisition of the same asset or a “substantially identical” asset 30 days before or 30 days after the sale at a loss denies the loss on the tax return. This is a very logical rule, considering the potential for abuse. Here’s an example:

Example 1: Sal owns 30 shares of Acme Corporation stock. He purchased it for $200 per share, and it is now worth $140 per share. Without the wash sale rule, Sal could sell all 30 shares for $140 on December 1st (triggering a $1,800 loss on his tax return) and then purchase 30 shares of Acme Corporation on December 2nd for its current value and have very little change in his economic position. 

Seen through the lens of Sal’s example, the wash sale rule makes sense. Why should Sal get to claim a loss on 30 shares of Acme stock he owns at year-end?

However, the wash sale rule can be implicated in less clear cut situations. Here’s one example:

Example 2: Cate owns 500 shares of IBM stock* in her taxable brokerage account. She purchased each share for $150 per share. On July 6, 2022, she sold 300 shares for $140 per share, realizing a $3,000 capital loss (300 times $10 loss per share). On July 29, 2022, IBM paid a dividend of $3 per share ($600 total on Cate’s remaining 200 shares), which Cate automatically reinvested in IBM stock, now valued again at $150 per share. 

In Cate’s case, the dividend reinvestment purchased 4 shares of IBM stock within the 61-day wash sale window. The taxable loss on 4 shares of the 300 sold ($40 total) is disallowed by the wash sale rule, and Cate will only be able to claim a taxable loss of $2,960 on the July 6th sale. 

* All values used in this blog post are hypothetical for purposes of the example. I did not look up IBM’s actual stock prices on these dates. The IBM dividend is also made up for the sake of the example.

One interesting tidbit about the wash sale rule in today’s environment: as the rule only applies to “securities” it does not apply to cryptocurrencies. Thus, an investor can sell a cryptocurrency at a loss on one day and repurchase it a day later and claim the entire loss on his or her tax return. There are proposals to do away with this treatment and subject cryptocurrencies to the wash sale rule. 

Retirement Accounts and the Wash Sale Rule

Let’s change Cate’s example just a bit, by having the repurchase occurring inside a Roth IRA.

Example 3: Cate owns 300 shares of IBM stock in her taxable brokerage account. She purchased each share for $150 per share. On July 6, 2022, she sold all 300 shares for $140 per share, realizing a $3,000 capital loss (300 times $10 loss per share). Separately, Cate owns 200 shares of IBM in her Roth IRA. On July 29, 2022, IBM paid a dividend of $3 per share ($600 total on Cate’s remaining 200 shares), which Cate’s Roth IRA automatically reinvested in IBM stock, now valued again at $150 per share. 

What result? The IRS has issued a Revenue Ruling, Rev. Rul. 2008-5, ruling that if the repurchase occurs inside the taxpayer’s Roth IRA or traditional IRA, the wash sale rule applies. Cate would suffer the exact same $40 wash sale rule loss disallowance. 

Note that a Revenue Ruling is not binding on taxpayers and the courts. Of course, a judge or appellate court may agree with the conclusion the IRS reaches in a Revenue Ruling, but they are not obligated to do so based solely on the IRS having issued the ruling. Rev. Rul. 2008-5 cites two 1930s court cases as authority for the conclusion reached in the ruling. Those cases involve a taxpayer using a controlled corporation to attempt to get around the wash sale rule, and the courts ruled that the wash sale rule applied regardless. 

In my research, I have not found any published court cases which have weighed in on Rev. Rul. 2008-5. The wash sale rule, as found in Section 1091, does not explicitly deem a retirement account and its owner to be the same person. Thus, there is at least some (perhaps quite small) risk to the IRS that a court would deem the primary result in Rev. Rul. 2008-5 to be too much of a stretch. That said, I certainly would not recommend taking a position counter to the ruling. I would struggle to advise that the wash sale rule does not apply if the security is repurchased in a retirement account. 

Disappearing Basis?

The wash sale rule disallows a loss, but it does not disallow basis. Section 1091(d) of the Internal Revenue Code and Treasury Regulation Section 1.1091-2 provide for a tax basis adjustment so that taxpayers are ultimately made whole after the application of the wash sale rule. Broadly speaking, the tax rules allow the disallowed loss to be added to the basis of the repurchased asset. In my Example 2 above, the basis of the 4 shares Cate repurchased is their historic cost ($150 per share) increased by the $10 per share disallowed loss. Thus, if Cate later sells those 4 shares, she will have a basis of $160 in those shares for purposes of determining gain or loss. 

In theory, the wash sale rule is simply a timing rule. It is inappropriate to allow a taxpayer to currently claim a loss when they wind up holding the exact same stock or securities. But, over time the tax basis rules should work out such that ultimately the correct amount is taxed to the taxpayer. 

What about basis adjustments when the wash sale occurs because of a repurchase made inside a retirement account? Rev. Rul. 2008-5 states that there is no basis adjustment with respect to a retirement account. There is an argument that Section 1091(d) should create Pro-Rata Rule basis in a traditional IRA. However, considering how highly technical and structured IRAs are, that is not a very likely outcome were the issue ever to be litigated. Further, that outcome would (quite oddly) give the taxpayer a different basis result based on whether they repurchased in a Roth retirement account or a traditional retirement account.

So what becomes of the basis? Does it just disappear? If the basis vanishes, the taxpayer obtains a worse wash sale result by repurchasing inside a retirement account. It seems odd that a taxpayer would receive a worse outcome for doing a repurchase through a retirement account instead of through a taxable brokerage account. 

Solving the Disappearing Basis Mystery

I have a theory that might solve the mystery. 

To get us started, consider that neither the Revenue Ruling nor Example 3 above discuss the “replacement property” in the taxable brokerage account. Here are two examples to ponder.

Example 4: Tim owns 1,000 shares of Domestic Equity Mutual Fund A (worth $50,000) he purchased for $60,000. It is held in a taxable brokerage account. On December 1, 2022, he sold Domestic Equity Mutual Fund A for $50,000 cash. He used the cash received to fund living expenses (food, clothing, heating bills, travel expenses, insurance, gasoline, etc.). On December 2, 2022, Tim purchased 1,000 shares of Domestic Equity Mutual Fund A in his Roth IRA. 

Example 5: Tim owns 1,000 shares of Domestic Equity Mutual Fund A (worth $50,000) he purchased for $60,000. It is held in a taxable brokerage account. On December 1, 2022, he exchanged all of his Domestic Equity Mutual Fund A for $50,000 worth of International Equity Mutual Fund B. On December 2, 2022, Tim purchased 1,000 shares of Domestic Equity Mutual Fund A in his Roth IRA. 

The wash sale rule disallows the $10,000 capital loss in both Example 4 and Example 5. But does Tim lose $10,000 of basis permanently? If he does, it’s an odd result considering that had he repurchased Domestic Equity Mutual Fund A in a taxable brokerage account (instead of in a retirement account), he would not lose that basis. 

I believe that there is a reasonable possibility that a court would rule that the $10,000 of basis shifts to the replacement property received in the wash sale. In Example 4, that conclusion leads Tim to no better position: he uses the cash for personal expenses, and there is no tax deduction for personal expenses. Further, I can’t imagine a court would give a step up in basis in Tim’s functional currency, the U.S. dollar. 

As applied to Example 5, where there has been a reinvestment in a taxable brokerage account, the equities of the situation might encourage some judges to find that Tim’s International Equity Mutual Fund B basis at a later sale is $60,000, not $50,000. 

Tim originally had $60,000 of basis in the system. While it is appropriate for a current loss to be disallowed, it is not appropriate for Tim’s basis in the system to be diminished in a situation where his overall taxable investment has not changed.

It’s one thing for the wash sale rule to operate to deny Tim a current loss deduction. It’s entirely another thing to interpret the wash sale rule to both deny current loss recognition and to permanently deny Tim $10,000 of basis. In its enactments of the wash sale rule and of the basis rules, Congress never manifested an intention for this one-two punch to bite Tim twice. If Tim sells the International Equity Mutual Fund B shares and recovers only $50,000 of basis he is inappropriately overtaxed. 

I believe some judges might determine that the IRS cannot have its cake (wash sale loss disallowance) and eat it too (permanent basis reduction). Basis exists to appropriately tax property transactions. Allowing Tim only $50,000 of future basis recovery over-taxes a later sale of his International Equity Mutual Fund B shares. While the IRS has a good argument that the wash sale rule disallowance should be spread to retirement account repurchases, it does not have a good argument that the overall result should be worsened if the repurchase occurs inside a retirement account.

Further, there is at least some risk to the IRS that a court would consider them to have reached just a bit by applying the wash sale rule to a repurchase inside a retirement account. The court might determine that what is good for the goose is good for the gander: if the IRS can reach a bit to apply the wash sale rule, the taxpayer can reach a bit to adjust the basis of the newly acquired securities in the taxable account.

The policies behind the rules point in the direction of allowing a taxpayer to add the disallowed loss to the basis of any replacement capital asset obtained through a direct exchange or a close-in-time use of the sales proceeds.

My proposed resolution has basis behave as it does in more familiar contexts. Say you received $50 from your grandmother when you were 12 years old. If you spent it on movie tickets and going bowling, the basis vanished for tax purposes. What if, instead, you purchased one share of stock of a publicly traded company for that $50? You’d get $50 of basis in that share of stock. Same with your first job: if you spend your first $1,000 W-2 paycheck on rent and groceries, tax basis disappears. But if you take that $1,000 and buy shares of ABC Mutual Fund in a taxable brokerage account, the basis stays attached to the mutual fund shares. Basis surviving when assets are reinvested in capital assets is a logical outcome.

Conclusion

Does anyone know for sure what happens to basis when the wash sale rule is tripped due to a repurchase in a retirement account? I believe it is still an unsolved mystery. 

Does basis vanish into the night? Or can it be preserved if the taxpayer reinvests in a capital asset in a brokerage account, as I have suggested?

Remember, the text of the Revenue Ruling does not affirmatively state that the basis simply disappears. Rather, all it says is that the basis does not get added to the taxpayer’s basis in the retirement account. To my mind, that’s a clue. It is not a definitive answer to the mystery. 

Now that we are 14 years removed from the issuance of Rev. Rul. 2008-5, it might be time for the IRS and Treasury Department to revisit the basis issue. The government could issue a regulation or another Revenue Ruling addressing the basis result in a situation similar to my Example 5. 

Of course, for taxpayers, this mystery is best avoided if possible. Repurchases should either (i) occur outside of the 61-day wash sale window or (ii) be of securities that are not the same or substantially identical to the sold securities.

I’ve also posted a video on YouTube with thoughts on this topic.

Lastly, the above is simply my technical analysis. It is not legal advice applicable to any one particular taxpayer or real life situation. 

FI Tax Guy can be your financial planner! Find out more by visiting mullaneyfinancial.com

Follow me on Twitter at @SeanMoneyandTax

This post is for entertainment and educational purposes only. It does not constitute accounting, financial, legal, or tax advice. Please consult with your advisor(s) regarding your personal accounting, financial, legal, and tax matters. Please also refer to the Disclaimer & Warning section found here.

Four Ways to Fight Inflation

Decisions you make today can subject you to more inflation tomorrow! Read below about ways to increase or decrease your exposure to inflation tomorrow.

Watch me discuss fighting back against inflation.

Tax Planning

As a practical matter, most Americans have the majority of their retirement savings in traditional, pre-tax vehicles such as the 401(k). Having money in a traditional 401(k) is not a bad thing. However, the traditional 401(k) involves trade offs: an upfront tax deduction is the primary benefit in exchange for future taxation when there is a withdrawal or Roth conversion.

Having money inside traditional retirement accounts subjects future inflation to taxation. Some of the future growth in a traditional retirement account is likely to be attributable to inflation, and thus there will be a tax on inflation. Further, there are no inflation adjustments when it comes to the taxation of traditional IRA and traditional 401(k) withdrawals. 

An antidote to this problem is the tax free growth offered by Roth accounts and health savings accounts. Getting money into Roths and HSAs excuses future growth from taxation, including growth attributable to inflation. 

Roth 401(k) versus Roth IRA

Of course, inflation is only one consideration. Many will do some traditional retirement account contributions and some Roth retirement account contributions. The question then arises: which Roth account to use? 

My view is that for many a Roth IRA contribution (whether a direct annual contribution or a Backdoor Roth IRA) is better than a Roth 401(k) contribution. Many do not qualify to deduct a traditional IRA contribution but can deduct a traditional 401(k) contribution. Considering that reality, why not combine a deductible traditional 401(k) contribution and a Roth IRA contribution? 

Long Term Fixed Rate Debt

Often we discuss how inflation hurts Americans, and we should be concerned about the bad effects of inflation. However, there is a way to become a beneficiary of inflation: using long-term, low interest fixed rate debt to your advantage.

That’s right: hold onto that low rate 30 year mortgage like it’s a life raft! Okay, that’s a bit hyperbolic, but the overall point holds. Inflationary environments are great for debtors, particularly those debtors who have locked in a low interest rate for a long term.

Here is an example: Sarah and Mike have a 30 year, $400,000 mortgage on their primary residence at a 2.9% fixed interest rate. By paying the required monthly payment, and no more, they benefit from any future inflation. By paying off the mortgage later rather than sooner, they are using devalued future money to pay the mortgage rather than more valuable current day dollars. 

Sarah and Mike benefit from inflation! Are there reasons to pay off a mortgage early? Sure. But in an inflationary environment, paying off the mortgage early gives the bank more valuable dollars to satisfy the debt.

To my mind, a fixed rate, long term mortgage is a great hedge against inflation.

That said, there are few perfect financial planning tactics. Most involve risk trade offs. One risk Sarah and Mike assume by not paying down the mortgage early is the risk of deflation. To obtain this inflation hedge, they expose themselves to the risk of deflation. If the U.S. dollar starts to deflate (i.e., it appreciates in value), Sarah and Mike will find themselves paying more valuable dollars to the bank in the future. 

Travel Rewards

Travel rewards can help fight inflation. One way is using sign-up bonuses and other accrued points to pay for hotel room nights or flights. Using points gets out of cash paying and thus inflation of the dollar hurts a bit less.

However, keep in mind that travel reward points are subject to their own inflation! The hotel chain or airline can devalue the redemption value of points at any time. Thus, if everything else is equal, those with significant travel rewards point balances might want to spend those points sooner rather than later for travel. 

A second consideration are the features of credit cards. Some travel branded credit cards come with certificates for free nights or a companion pass for a companion to receive free or discounted flights. If flighting inflation is a key goal, favoring cards that offer free-night certificates or companion passes can be a way to fight inflation. 

Spending that Leads to More or Less Future Spending

We’re used to assessing the price tag. $28,000 for that brand new car: “that’s a great deal!” or “that’s a terrible deal!” But the price tag is only one part of the financial picture.

If you buy a black cup of coffee at Starbucks, it might cost you $2.65. Fortunately, that’s it. The cup of coffee isn’t likely to cause you to incur later costs.

What about a $45,000 SUV? That purchase will cause later costs, many significant. For example, the cost to insure a $45,000 SUV might be significantly more than insuring a $22,000 sedan. What about gas? By purchasing a larger, less fuel-efficient car, you lock in more future spending, and thus more exposure to future inflation. 

Think about buying a large home with a pool in the backyard. That square footage attracts property tax, heating and cooling costs, and inflation in both costs. The pool in the backyard requires constant upkeep, subjecting the homeowner to another source of inflation. 

To my mind, food is a big one in the fight against inflation. What you eat today could very well translate into medical costs tomorrow, exposing you to significant inflation. Spending on foods with vegetable oils and sugars today is likely to increase your future exposure to medical expense inflation. 

The lesson is this: you can use today’s spending to reduce your exposure to future inflation. 

Conclusion

Is there a perfect answer to inflation? No. But with some intentional planning and spending today, Americans can reduce their exposure to the harmful effects of future inflation. 

FI Tax Guy can be your financial planner! Find out more by visiting mullaneyfinancial.com

Follow me on Twitter: @SeanMoneyandTax

This post is for entertainment and educational purposes only. It does not constitute accounting, financial, investment, legal, or tax advice. Please consult with your advisor(s) regarding your personal accounting, financial, investment, legal, and tax matters. Please also refer to the Disclaimer & Warning section found here. 

72(t) Series of Substantially Equal Periodic Payments Update

The IRS and Treasury have recently issued two updates to the rules for payments which avoid the 10 percent early withdrawal penalty from retirement accounts. These payments are referred to as a series of substantially equal periodic payments, SEPP, or 72(t) payments. This post discusses the updated rules. 

72(t) Payments

Tax advantaged retirement accounts are fantastic. Who doesn’t love 401(k)s, IRAs, Roth IRAs, and the like?

However, investing through a tax advantaged account can have drawbacks. One big drawback is that taxable amounts withdrawn from a tax advantaged retirement account prior to the account owner turning age 59 ½ are generally subject to a 10 percent early withdrawal penalty. My home state of California adds a 2.5 percent early withdrawal penalty. 

There are some exceptions to this penalty. One of them is taking 72(t) payments. The idea is that if the taxpayer takes a “series of substantially equal periodic payments” they can avoid the penalty. 

72(t) payments must be taken annually. Further, they must last for the longer of (a) 5 years or (b) the time until the taxpayer turns age 59 ½. This creates years of locked-in taxable income. 

There are three methods that can be used to compute the amount of the annual 72(t) payments. These methods compute an annual distribution amount generally keyed off three numbers: the balance in the relevant retirement account, the interest rate, and the table factor provided by the IRS. The factor is greater the younger the account owner is. The greater the factor, the less the account owner can withdraw from a retirement account in a 72(t) payment.

New 72(t) Payment Interest Rates

In January 2022, the IRS and Treasury issued Notice 2022-6. Hat tip to Ed Zollars for the alert. This notice provides some new 72(t) rules. The biggest, and most welcome, change is a new rule for determining the interest rate.

Previously, the rule had been that 72(t) payments were keyed off 120 percent of the mid-term applicable federal rate (“AFR”). The IRS publishes this rate every month. In recent years, that has been somewhat problematic, as interest rates have been historically low. For example, in September 2020, the mid-term AFR was just 0.42 percent. This made relying on a 72(t) payment somewhat perilous. How much juice can be squeezed from a large retirement account if the interest rate is just 0.42 percent?

Here is what a $1M traditional IRA could produce, under the fixed amortization method, in terms of an annual payment for a 53 year old starting a 72(t) payment if the interest rate is just 0.42 percent:

120% of Sept 2020 MidTerm AFR0.42%
Single Life Expectancy Years at Age 5333.4
Account Balance$1,000,000.00
Annual Payment$32,151.93

Notice 2022-6 makes a very significant change. It now allows taxpayers to pick the greater of (i) up to 5 percent or (ii) up to 120 percent of mid-term AFR. That one change makes a 72(t) payment a much more attractive option, since periods of low interest rates do not as adversely affect the calculation. 

Here is what a $1M traditional IRA could produce, under the fixed amortization method, in terms of an annual payment for a 53 year old starting a 72(t) payment if the interest rate is 5 percent:

5% Interest Rate5.00%
Single Life Expectancy Years at Age 5333.4
Account Balance$1,000,000.00
Annual Payment$62,189.80

The new rule provides a 5 percent interest rate floor for those using the fixed amortization method and the fixed annuitization method to compute a 72(t) payment. Using a 5 percent interest rate under the fixed amortization method is generally going to produce a greater payment amount than using the required minimum distribution method for 72(t) payments. 

The interest rate change provides taxpayers with much more flexibility with 72(t) payments, and a greater ability to extract more money penalty free prior to age 59 ½. Taxpayers already have the ability to “right-size” the traditional IRA out of which to take a 72(t) payment to help the numbers work out. In recent years, what has been much less flexible has been the interest rate. Under these new rules, taxpayers always have the ability to select anywhere from just above 0% to 5% regardless of what 120 percent of mid-term AFR is. 

Watch me discuss the update to 72(t) payment interest rates.

New Tables

A second new development is that the IRS and Treasury have issued new life expectancy tables for required minimum distributions (“RMDs”) and 72(t) payments. Most of the new tables are found at Treasury Regulation Section 1.401(a)(9)-9, though one new table is found at the end of Notice 2022-6. 

These tables reflect increasing life expectancies. As a result, they reduce the amount of RMDs, as the factors used to compute RMDs are greater as life expectancy increases. 

From a 72(t) payment perspective, this development is a minor taxpayer unfavorable development. Long life expectancies in the tables means the tables slightly reduce the amount of juice that can be squeezed out of any particular retirement account.

This said, the downside to 72(t) payments coming from increasing life expectancy on the tables is more than overcome by the ability to always use an interest rate of up to 5 percent. These two developments in total are a great net win for taxpayers looking to use 72(t) payments during retirement. 

Use of 72(t) Payments

Traditionally, I have viewed 72(t) payments as a life raft rather than as a desirable planning tool for those retiring prior to their 59 ½th birthday. Particularly for those in the FI community, my view has been that it is better to spend down taxable assets and even dip into Roth basis rather than employ a 72(t) payment plan. 

These developments shift my view a bit. Yes, I still view 72(t) payments as a life raft. Now it is an upgraded life raft with a small flatscreen TV and mini-fridge. 😉

As a practical matter, some will get to retirement prior to age 59 ½ with little in taxable and Roth accounts, and the vast majority of their financial wealth in traditional retirement accounts. Notice 2022-6 just made their situation much better and much more flexible. Getting to retirement at a time of very low interest rates does not necessarily hamstring their retirement plans given that they will always have at least a 5 percent interest rate to use in calculating their 72(t) payments. 

72(t) Payments and Roth IRAs

As Roth accounts grow in value, there will be at least some thought of marrying Roth IRAs with 72(t) payments. 

At least initially, Roth IRAs have no need for 72(t) payments. Those retired prior to age 59 ½ can withdraw previous Roth contributions and Roth conversions aged at least 5 years at any time tax and penalty free for any reason. So off the bat, no particular issue, as nonqualified distributions will start-off as being tax and penalty free.

Only after all Roth contributions have been withdrawn are Roth conversions withdrawn, and they are withdrawn first-in, first-out. Only after all Roth conversions are withdrawn does a taxpayer withdraw Roth earnings.  

For most, the odds of withdrawing (i) Roth conversions that are less than five years old, and then (ii) Roth earnings prior to age 59 ½ are slim. But, there could some who love Roths so much they largely or entirely eschew traditional retirement account contributions. One could imagine an early retiree with only Roth IRAs. 

Being “Roth only” prior to age 59 ½ could present problems if contributions and conversions at least 5 years old have been fully depleted. Taxpayers left with withdrawing conversions less than 5 years old or earnings in a nonqualified distribution might opt to establish a 72(t) payment plan for their Roth IRA. Such a 72(t) payment plan could avoid the 10 percent penalty on the withdrawn amounts attributable insufficiently aged conversions or Roth earnings. Note, however, that Roth earnings withdrawn in a nonqualified distribution are subject to ordinary income tax, regardless of whether they are part of a 72(t) payment plan. 

See Treasury Regulation Section 1.408A-6 Q&A 5 providing that Roth IRA distributions can be subject to both the 72(t) early withdrawal penalty and the exceptions to the 72(t) penalty. The exceptions include a 72(t) payment plan. 

Additional Resource

Ed Zollars has an excellent post on the updated IRS rules for 72(t) payments here.

FI Tax Guy can be your financial planner! Find out more by visiting mullaneyfinancial.com

Follow me on Twitter: @SeanMoneyandTax

This post is for entertainment and educational purposes only. It does not constitute accounting, financial, investment, legal, or tax advice. Please consult with your advisor(s) regarding your personal accounting, financial, investment, legal, and tax matters.Please also refer to the Disclaimer & Warning section found here.

FI Tax Guy Featured on the Optimal Finance Daily Podcast

Today and tomorrow my year-end tax planning post will be featured on the Optimal Finance Daily podcast.

Listen to today’s episode on podcast players and here.

Read my year-end tax planning blog post here.

FI Tax Guy can be your financial planner! Find out more by visiting mullaneyfinancial.com

Follow me on Twitter: @SeanMoneyandTax

This post is for entertainment and educational purposes only. It does not constitute accounting, financial, investment, legal, or tax advice. Please consult with your advisor(s) regarding your personal accounting, financial, investment, legal, and tax matters. Please also refer to the Disclaimer & Warning section found here. 

Sean Talks Tax with DocG

Listen to my discussion with DocG on the latest episode of the Earn and Invest podcast. Available on all major podcast players and at this link: https://www.earnandinvest.com/episodes/five-tax-questions-you-must-ask

FI Tax Guy can be your financial advisor! Find out more by visiting mullaneyfinancial.com

Follow me on Twitter: @SeanMoneyandTax

This post is for entertainment and educational purposes only. It does not constitute accounting, financial, investment, legal, or tax advice. Please consult with your advisor(s) regarding your personal accounting, financial, investment, legal, and tax matters. Please also refer to the Disclaimer & Warning section found here. 
Tax Planning for Inflation

In recent years, inflation existed but was not significant. Significant inflation was associated with wide lapels and eight-track tapes and thought to be left behind in the late 1970s and early 1980s.

But, sure enough, significant inflation is back. Inflation is 6.2 percent for the 12 months ending October 2021.  

Inflation has a tax angle. How does one use tax planning to minimize the impact of inflation? In this post, I review the issues associated with inflation and tactics to consider if one is concerned about inflation.

Inflation: The Tax Problem

Inflation increases the nominal (i.e., stated) value of assets without a corresponding increase in the real value of the asset. Here is an example:

Larry buys $100,000 worth of XYZ Mutual Fund on January 1, 2022. During the year 2022, there is 10 percent inflation. On January 1, 2023, the XYZ Mutual Fund is worth $110,000. Inflation-adjusted, the position has the same real value as it did when Larry purchased it. However, were Larry to sell the entire position, he would trigger a $10,000 capital gain ($110,000 sales price less $100,000 tax basis), which would be taxable to him. 

Hopefully you see the problem: Larry has not experienced a real increase in wealth. Larry’s taxable “gain” is not a gain. Rather, it is simply inflation! Larry will pay tax on inflation if he sells the asset. Ouch!

While inflation increases the nominal value of assets, there is no inflation adjustment to tax basis! Thus, inflation creates artificial gains subject to income tax. 

There are other tax problems with inflation. Inflation artificially increases amounts received as wages, self-employment income, interest, dividends, and retirement plan distributions. Those artificial increases are not real increases in income (as they do not represent increases in value) but they are subject to income tax as though they were real increases in income.

The tax law does provide some remedy to address the problem of taxing inflation. The IRS provides inflation adjustments to increase the size of progressive tax brackets. In addition, the standard deduction is adjusted annually for inflation. Recently the IRS released the inflation adjustments for 2022.  

IRS inflation adjustments are helpful, but they do not excuse inflation from taxation. Rather, they only soften the blow. Thus, they are not a full cure for the tax problems caused by inflation. 

Inflation and Traditional Retirement Accounts

Inflation is detrimental to traditional retirement accounts such as pre-tax 401(k)s and IRAs. Holding assets inside a traditional retirement account subjects the taxpayer to income tax on the growth in the assets caused by inflation.

Inflation artificially increases amounts in these accounts that will ultimately be subject to taxation. Inflation can also limit the opportunity to do Roth conversions in early retirement. Greater balances to convert from traditional to Roth accounts and increased dividend, capital gain, and interest income triggered by inflation makes early retiree Roth conversion planning more challenging. 

Inflation and Real Estate

There are several tax benefits of rental real estate. One of the main benefits is depreciation. For residential real estate, the depreciable basis is deducted in a straight-line over 27.5 years. For example, if the depreciable basis of a rental condo is $275,000, the annual depreciation tax deduction (for 27.5 years) is $10,000 (computed as $275,000 divided by 27.5). That number rarely changes, as most of the depreciable basis is determined at the time the property is purchased or constructed. 

Over time, inflation erodes the value of depreciation deductions. Inflation generally increases rental income, but the depreciation deduction stays flat nominally and decreases in real value. Increasing inflation reduces the tax benefits provided by rental real estate. 

Planning Techniques

There are planning techniques that can protect taxpayers against the tax threat posed by inflation. 

Roth Contributions and Conversions

Inflation is yet another tax villain the Roth can slay. Tax free growth inside a Roth account avoids the tax on inflation. 

Once inside a Roth, concerns about inflation increasing taxes generally vanish. Properly planned, Roths provide tax free growth and tax free withdrawals. Thus, Roths effectively eliminate the concern about paying tax on inflation. 

For those thinking of Roth conversions, inflation concerns point to accelerating Roth conversions. The sooner amounts inside traditional retirement accounts are converted to Roth accounts, the less exposure the amounts have to inflation taxes. 

Roth contributions and conversions provide tax insurance against the threat of inflation. For those very concerned about inflation, this consideration moves the needle toward the Roth in the ongoing Roth versus traditional debate. 

Watch me discuss using Roth accounts to help manage an investor’s exposure to inflation.

Health Savings Accounts

A Health Savings Account, like its Roth IRA cousin, offers tax free growth. HSAs also protect against taxes on inflation. Inflation is another argument to take advantage of an HSA. 

Basis Step Up Planning

There is another tax planning opportunity that can wipe away the taxes owed on years of inflation: the basis step up at death. At death, heirs receive a basis in inherited taxable assets which is usually the fair market value of the assets on the date of death. For taxable assets, death provides an opportunity to escape the tax on inflation.

It is important to note that traditional retirement accounts do not receive a basis step up. Inflation inside a traditional retirement account will eventually be subject to tax (either to the original owner or to a beneficiary after the original owner’s death). 

During one’s lifetime, there is the tax gain harvesting opportunity to step up basis and reduce inflation taxes. The tactic is to sell and repurchase an investment with a built-in gain at a time when the investor does not pay federal income tax on the capital gain. If one can keep their marginal federal income tax rate in the 12% or lower marginal tax bracket, they can pay a 0% federal income tax rate on the gain and “reset” the basis to the repurchase price of the sold and then repurchased asset. 

There is a second flavor of tax gain harvesting: triggering a capital gain (at an advantageous time from a tax perspective) by selling an asset and reinvesting the proceeds in a more desirable asset (essentially, investment reallocation). 

One inflation consideration with respect to tax gain harvesting: as inflation increases interest and dividends, there will be less room inside the 12 percent taxable income bracket to create capital gains that are federal income tax free.

Conclusion

Inflation is yet another tax planning consideration. As we are now in a period of significant inflation, taxpayers and advisors will need to weigh inflation’s potential impact on tax strategies. 

None of the above is advice for any particular taxpayer. Hopefully it provides some educational background to help assess the tax impact of inflation and consider tactical responses to inflation.

FI Tax Guy can be your financial planner! Find out more by visiting mullaneyfinancial.com

Follow me on Twitter: @SeanMoneyandTax

This post is for entertainment and educational purposes only. It does not constitute accounting, financial, investment, legal, or tax advice. Please consult with your advisor(s) regarding your personal accounting, financial, investment, legal, and tax matters. Please also refer to the Disclaimer & Warning section found here.

2021 YEAR-END TAX PLANNING

It’s time to think about year-end tax planning. Year-end is a great time to get tax planning ducks in a row and take advantage of opportunities. This is particularly true for those in the financial independence community. FI principles often increase one’s tax planning opportunities.  

Remember, this post is for educational purposes only. None of it is advice directed towards any particular taxpayer. 

Backdoor Roth IRA Deadline 2021

As of now (December 7, 2021), the legal deadlines around Backdoor Roth IRAs have not changed: the nondeductible 2021 traditional IRA contribution must happen by April 18, 2022 and there is no legal deadline for the second step, the Roth conversion. However, from a planning perspective, the practical deadline to have both steps of a 2021 Backdoor Roth IRA completed is December 31, 2021. 

This is because of proposed legislation that eliminates the ability to convert nondeductible amounts in a traditional IRA effective January 1, 2022. As of December 7th, the proposed legislation has passed the House of Representatives but faces a very certain future in the Senate. Considering the risk that the Backdoor Roth elimination proposal is enacted, taxpayers planning on completing a 2021 Backdoor Roth IRA should act to ensure that the second step of the Backdoor Roth IRA (the Roth conversion) is completed before December 31st. 

Taxpayers on the Roth IRA MAGI Limit Borderline

In years prior to 2021, taxpayers unsure of whether their income would allow them to make a regular Roth IRA contribution could simply wait until tax return season to make the determination. At that point, they could either make the regular Roth IRA contribution for the prior year (if they qualified) or execute what I call a Split-Year Backdoor Roth IRA.  

With the proposed legislation looming, waiting is not a good option. The good news is that taxpayers executing a Backdoor Roth IRA during a year they actually qualify for a regular annual Roth IRA contribution suffer no material adverse tax consequences. Of course, in order for this to be true there must be zero balance, or at most a very small balance, in all traditional IRAs, SEP IRAs, and SIMPLE IRAs as of December 31, 2021. 

December 31st and Backdoor Roth IRAs

December 31st is a crucial date for those doing the Roth conversion step of a Backdoor Roth IRA during the year. It is the deadline to move any balances in traditional IRAs, SEP IRAs, and SIMPLE IRAs to workplace plans in order to ensure that the Roth conversion step of any Backdoor Roth IRA executed during the year is tax-efficient. 

This December 31st deadline applies regardless of the proposed legislation discussed above. 

IRAs and HSAs

Good news on regular traditional IRA contributions, Roth IRA contributions, and HSA contributions: they don’t have to be part of an end-of-2021 tax two-minute drill. The deadline for funding an HSA, a traditional IRA, and a Roth IRA for 2021 is April 18, 2022. 

Solo 401(k)

The self-employed should consider this one. Deadlines vary, but as a general rule, those eligible for a Solo 401(k) usually benefit from establishing one prior to year-end. The big takeaway should be this: if you are self-employed, your deadline to seriously consider a Solo 401(k) for 2021 is ASAP! Usually, such considerations benefit from professional assistance. 

Something to look forward to in 2022: my upcoming Solo 401(k) book!

Charitable Contributions

For those itemizing deductions in 2021 and either not itemizing in 2022 or in a lower marginal tax rate in 2022 than in 2021, it can be advantageous to accelerate charitable contributions late in the year. It can be as simple as a direct donation to a qualifying charity by December 31st. Or it could involve contributing to a donor advised fund by December 31st.  

A great donor advised fund planning technique is transferring appreciated securities (stocks, bonds, mutual funds, or ETFs) to a donor advised fund. Many donor advised fund providers accept securities. The tax benefits of making such a transfer usually include (a) eliminating the built-in capital gain from federal income taxation and (b) if you itemize, getting to take a current year deduction for the fair market value of the appreciated securities transferred to the donor advised fund. 

The elimination of the lurking capital gain makes appreciated securities a better asset to give to a donor advised fund than cash (from a tax perspective). Transfers of appreciated securities to 501(c)(3) charities can also have the same benefits.

The 2021 deadline for this sort of planning is December 31, 2021, though taxpayers may need to act much sooner to ensure the transfer occurs on time. This is particularly true if the securities are transferred from one financial institution to a donor advised fund at another financial institution. In these cases, the transfer may have to occur no later than mid-November, though deadlines will vary.

Early Retirement Tax Planning

For those in early retirement, the fourth quarter of the year is the time to do tax planning.  Failing to do so can leave a great opportunity on the table. 

Prior to taking Social Security, many early retirees have artificially low taxable income. Their only taxable income usually consists of interest, dividends, and capital gains. In today’s low-yield environment, without additional planning, early retirees’ taxable income can be very low (perhaps even below the standard deduction). 

Artificially low income gives early retirees runway to fill up lower tax brackets (think the 10 percent and 12 percent federal income tax brackets) with taxable income. Why pay more tax? The reason is simple: choose to pay tax when it is taxed at a low rate rather than defer it to a future when it might be taxable at a higher rate.

The two main levers in this regard are Roth conversions and tax gain harvesting. Roth conversions move amounts in traditional retirement accounts to Roth accounts via a taxable conversion. The idea is to pay tax at a very low tax rate while taxable income is artificially low, rather than leaving the money in deferred accounts to be taxed later in retirement at a higher rate under the required minimum distribution (“RMD”) rules. 

Tax gain harvesting is selling appreciated assets when one is in the 10 percent or 12 percent marginal tax bracket so as to incur a zero percent long term capital gains federal tax rate on the capital gain. 

Early retirees can do some of both. In terms of a tiebreaker, if everything else is equal, I prefer Roth conversions to tax gain harvesting, for two primary reasons. First, traditional retirement accounts are subject to ordinary income tax rates in the future, which are likely to be higher than preferred capital gains tax rates. Second, large taxable capital gains in taxable accounts can be washed away through the step-up in basis at death. The step-up in basis at death doesn’t exist for traditional retirement accounts. 

One time to favor tax gain harvesting over Roth conversions is when the traditional retirement accounts have the early retiree’s desired investment assets but the taxable brokerage account has positions that the early retiree does not like anymore (for example, a concentrated position in a single stock). Why not take advantage of tax gain harvesting to reallocate into preferred investments in a tax-efficient way?

Long story short: during the fourth quarter, early retirees should consider their taxable income for the year and consider year-end Roth conversions and/or tax gain harvesting. Planning in this regard should be executed no later than December 31st, and likely earlier to ensure proper execution. 

Roth Conversions, Tax Gain Harvesting, and Tax Loss Harvesting

Early retired or not, the deadline for 2021 Roth conversions, tax gain harvesting, and tax loss harvesting is December 31, 2021. Taxpayers should always consider timely implementation: these are not tactics best implemented on December 30th! 

For some who find their income dipped significantly in 2021 (perhaps due to a job loss), 2021 might be the year to convert some amounts in traditional retirement accounts to Roth retirement accounts. Some who are self-employed might want to consider end-of-year Roth conversions to maximize their qualified business income deduction. 

Stimulus and Child Tax Credit Planning

Taxpayers who did not receive their full 2021 stimulus may want to look into ways to reduce their 2021 adjusted gross income so as to qualify for additional stimulus funds. I wrote in detail about one such opportunity in an earlier blog post. Lowering adjusted gross income can also qualify taxpayers for additional child tax credits. 

There are many factors you and your advisor should consider in tax planning. This opportunity may be one of them. For example, taxpayers considering a Roth conversion at the end of the 2021 might want to hold off in order to qualify for additional stimulus and/or child tax credits. 

Accelerate Payments

The self-employed and other small business owners may want to review business expenses and pay off expenses before January 1st, especially if they anticipate their marginal tax rate will decrease in 2022. Depending on structure and accounting method, doing so may not only reduce income taxes, it could also reduce self-employment taxes. 

State Tax Planning

For my fellow Californians, the big one here is property taxes. It may be advantageous to pay billed (but not yet due) property taxes in late 2021. This allows taxpayers to deduct the amount on their 2021 California income tax return. In California, the standard deduction ($4,601 for single taxpayers, $9,202 for married filing joint taxpayers) is much lower than the federal standard deduction, so consideration should be given to accelerating itemized deductions in California, regardless of whether the taxpayer itemizes for federal income tax purposes.

Required Minimum Distributions (“RMDs”)

They’re back!!! RMDs are back for 2021. The deadline to withdraw a required minimum distribution for 2021 is December 31, 2021. Failure to do so can result in a 50 percent penalty. 

Required minimum distributions apply to most retirement accounts (Roth IRAs are an exception). They apply once the taxpayer turns 72. Also, many inherited retirement accounts (including Roth IRAs) are subject to RMDs, regardless of the beneficiary’s age. 

Planning for Traditional Retirement Accounts Inherited in 2020 and 2021

Those inheriting traditional retirement accounts in 2020 or later often need to do some tax planning. The end of the year is a good time to do that planning. Many traditional retirement account beneficiaries will need to empty the retirement account in 10 years (instead of being on an RMD schedule), and thus will need to plan out distributions over the 10 year time frame to manage taxes rate on the distributions.

2021 Federal Estimated Taxes

For those with small business income, side hustle income, significant investment income, and other income that is not subject to tax withholding, the deadline for 2021 4th quarter estimated tax payments to the IRS is January 18, 2022. Such individuals should also consider making timely estimated tax payments to cover any state income taxes. 

Review & Update Beneficiary Designation Forms

Beneficiary designation forms control the disposition of financial assets (such as retirement accounts and brokerage accounts) upon death. Year-end is a great time to make sure the relevant institutions have up-to-date forms on file. While beneficiary designations should be updated anytime there is a significant life event (such as a marriage or a death of a loved one), year-end is a great time to ensure that has happened. 

2022 and Beyond Tax Planning

The best tax planning is long term planning that considers the entire financial picture. There’s always the temptation to maximize deductions on the current year tax return. But the best planning considers your current financial situation and your future plans and strives to reduce total lifetime taxes. 2022 is as good a time as any to do long-term planning.

FI Tax Guy can be your financial planner! Find out more by visiting mullaneyfinancial.com

Follow me on Twitter: @SeanMoneyandTax

This post is for entertainment and educational purposes only. It does not constitute accounting, financial, investment, legal, or tax advice. Please consult with your advisor(s) regarding your personal accounting, financial, investment, legal, and tax matters. Please also refer to the Disclaimer & Warning section found here.

The Backdoor Roth IRA and December 31st

New Year’s Eve is an important day if you do a Backdoor Roth IRA. Read below to find out why.

The Backdoor Roth IRA

I’ve written before about the Backdoor Roth IRA. It is a two step process whereby those not qualifying for a regular Roth IRA contribution can qualify to get money into a Roth IRA. Done over several years, it can help taxpayers grow significant amounts of tax free wealth.

One of the best aspects of the Backdoor Roth IRA is that it does not forego a tax deduction. Most taxpayers ineligible to make a regular Roth IRA contribution are also ineligible to make a deductible traditional IRA contribution. In the vast majority of cases, the choice is between investing money in a taxable account versus investing in a Roth account. For most, a Roth is preferable, since Roths do not attract income taxes on the interest, dividends, and capital gains investments generate. 

The Basic Backdoor Roth IRA and the Form 8606

Let’s start with a fairly basic example. 

Example 1

Betsy, age 40, earns $300,000 from her W-2 job in 2021, is covered by a workplace 401(k) plan, and has some investment income. Betsy has no balance in a traditional IRA, SEP IRA, or SIMPLE IRA.

At this level of income, Betsy does not qualify for a regular Roth IRA contribution, and she does not qualify to deduct a traditional IRA contribution. 

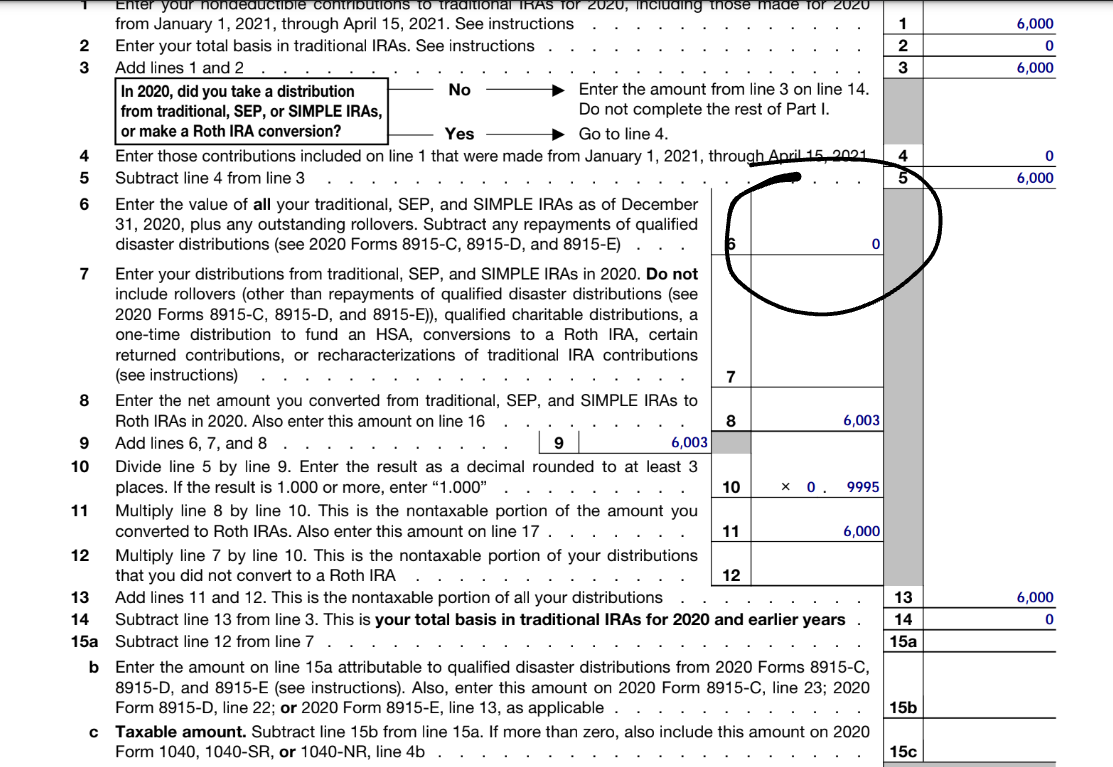
Betsy contributes $6,000 to a traditional IRA on May 20, 2021. The contribution is nondeductible. Because the contribution is nondeductible, Betsy gets a $6,000 basis in her traditional IRA. Betsy must file a Form 8606 with her 2021 tax return to report the nondeductible contribution.

On June 5, 2021, Betsy converts the entire balance in the traditional IRA, $6,003, to a Roth IRA. As of December 31, 2021, Betsy has no balance in a traditional IRA, SEP IRA, or SIMPLE IRA.

Betsy has successfully executed a Backdoor Roth IRA. Here is what page 1 of the Form 8606 Betsy should file with her 2021 income tax return should look like. 

Notice here that I am using the 2020 version of the Form 8606 for this and all examples. The 2021 Form 8606 is not yet available as of this writing. 

The most important line of page 1 of the Form 8606 is line 6. Line 6 reports the fair market value of all traditional IRAs, SEP IRAs, and SIMPLE IRAs Betsy owns as of year-end. Because Betsy had no traditional IRAs, SEP IRAs, and SIMPLE IRAs as of December 31, 2021, her Backdoor Roth IRA works and is tax efficient. This important number ($0) on line 6 of the Form 8606 is what ensures Betsy’s Backdoor Roth IRA is tax efficient. 

Note that Betsy’s Backdoor Roth IRA creates an innocuous $3 of taxable income, which is reported on the top of part 2 of the Form 8606. 

The Pro-Rata Rule and December 31st

But what if Betsy did have a balance inside a traditional IRA, SEP IRA, or SIMPLE IRA on December 31, 2021? Would her Backdoor Roth IRA still be tax efficient? Probably not, due to the Pro-Rata Rule.

The Pro-Rata Rule tells us just how much of the basis in her traditional IRA Betsy can recover when she does the Roth conversion step of the Backdoor Roth IRA. Betsy’s $6,000 nondeductible traditional IRA creates $6,000 of basis. As we saw above, Betsy was able to recover 100 percent of her $6,000 of basis against her Roth conversion. 

But the Pro-Rata Rule says “not so fast” if Betsy has another traditional IRA, SEP IRA, or SIMPLE IRA on December 31st of the year of any Roth conversion. The Pro-Rata Rule allocates IRA Basis between converted amounts (in Betsy’s case, $6,003) and amounts in traditional IRAs, SEP IRAs, and SIMPLE IRAs on December 31st. Here’s an example. 

Example 2

Betsy, age 40, earns $300,000 from her W-2 job in 2021, is covered by a workplace 401(k) plan, and has some investment income. Betsy has no balance in a traditional IRA, SEP IRA, or SIMPLE IRA.

Betsy contributes $6,000 to a traditional IRA on May 20, 2021. The contribution is nondeductible. Because the contribution is nondeductible, Betsy gets a $6,000 basis in her traditional IRA. Betsy must file a Form 8606 with her 2021 tax return to report the nondeductible contribution.

On June 5, 2021, Betsy converts the entire balance in the traditional IRA, $6,003, to a Roth IRA. 

On September 1, 2021, Betsy transfers an old 401(k) from a previous employer 401(k) plan to a traditional IRA. On December 31st, that traditional IRA is worth $100,000. The old 401(k) had no after-tax contributions. 

This one 401(k)-to-IRA rollover transaction dramatically changes both the taxation of Betsy’s Backdoor Roth IRA and her 2021 Form 8606. Here’s page 1 of the Form 8606.

Line 6 of the Form 8606 now has $100,000 on it instead of $0. That $100,000 causes Betsy to recover only 5.67 percent of the $6,000 of basis she created by making a nondeductible contribution to the traditional IRA. As a result, $5,663 of the $6,003 transferred to the Roth IRA in the Roth conversion step is taxable to Betsy as ordinary income. At a 35% tax rate, the 401(k) to IRA rollover (a nontaxable transaction) cost Betsy $1,982 in federal income tax on her Backdoor Roth IRA. Ouch!

Quick Lesson: The lesson here is that prior to rolling over a 401(k) or other workplace plan to an IRA, taxpayers should consider the impact on any Backdoor Roth IRA planning already done and/or planned for the future. One possible planning alternative is to transfer old employer 401(k) accounts to current employer 401(k) plans.

There is an antidote to the Pro-Rata Rule when one has amounts in traditional IRAs, SEP IRAs, and SIMPLE IRAs. It is transferring the traditional IRA, SEP IRA, or SIMPLE IRA to a qualified plan (such as a 401(k) plan) before December 31st. Here is what that might look like in Betsy’s example. 

Example 3

Betsy, age 40, earns $300,000 from her W-2 job in 2021, is covered by a workplace 401(k) plan, and has some investment income. Betsy has no balance in a traditional IRA, SEP IRA, or SIMPLE IRA.

Betsy contributes $6,000 to a traditional IRA on May 20, 2021. The contribution is nondeductible. Because the contribution is nondeductible, Betsy gets a $6,000 basis in her traditional IRA. Betsy must file a Form 8606 with her 2021 tax return to report the nondeductible contribution.

On June 5, 2021, Betsy converts the entire balance in the traditional IRA, $6,003, to a Roth IRA. 

On September 1, 2021, Betsy transfers an old 401(k) from a previous employer to a traditional IRA. The old 401(k) had no after-tax contributions. 

On November 16, 2021, Betsy transfers the entire balance in this new traditional IRA to her current employer’s 401(k) plan in a direct trustee-to-trustee transfer. 

Here is Betsy’s 2021 Form 8606 (page 1) after all of these events:

Betsy got clean by December 31st, so her Backdoor Roth IRA now reverts to the optimized result (just $3 of taxable income) she obtained in Example 1. 

Pro-Rata Rule Clean Up

Implementation 

From a planning perspective, it is best to clean up old traditional IRAs/SEP IRAs/SIMPLE IRAs prior to, not after, executing the Roth conversion step of a Backdoor Roth IRA. I say that because things happen in life. There is absolutely no guarantee that those intending to roll amounts from IRAs to workplace qualified plans will get that accomplished by December 31st. 

Further, transfers from one retirement account to another are usually best done through a direct “trustee-to-trustee” transfer to minimize the risk that the money in the retirement account accidentally is distributed to the individual, causing potential tax and penalties. 

Before cleaning up old traditional IRAs, SEP IRAs, and SIMPLE IRAs, one should consider the investment choices and fees inside their employer retirement plan (such as a 401(k)). If the investment options are not good, and/or the fees are high, perhaps cleaning up an IRA to move money into less desirable investments is not worth it. This is a subjective judgment that must weigh the potential tax and investment benefits and drawbacks. 

Tax Issues

Amazingly enough, the Pro-Rata Rule is concerned with only one day: December 31st. A taxpayer can have a balance in a traditional IRA, SEP IRA, or SIMPLE IRA on any day other than December 31st, and it does not count for purposes of the Pro-Rata Rule. Perhaps December 31st should be called Pro-Rata Rule Day instead of New Year’s Eve. 😉

Betsy’s November 16th distribution from her traditional IRA to the 401(k) plan does not attract any of the basis created by the nondeductible traditional IRA contribution earlier in the year. This document provides a brief technical explanation of why rollovers to qualified plans do not reduce IRA basis. 

Extra care should be taken when cleaning up (a) large amounts in any type of IRA and (b) any SIMPLE IRA. While it is fairly obvious that significant sums should be moved only after considering all the relevant investment, tax, and execution issues, the SIMPLE IRA provides its own nuances. Any SIMPLE IRA cannot be rolled to an account other than a SIMPLE IRA within the SIMPLE IRA’s first two years of existence. Thus, SIMPLE IRAs must be appropriately aged before doing any sort of Backdoor Roth IRA clean up planning. 

Spouses are entirely separate for Pro-Rata Rule purposes, even in community property states. Cleaning up one spouse, or failing to clean up one spouse, has absolutely no impact on the taxation of the other spouse’s Backdoor Roth IRA.

Lastly, non spousal inherited IRAs do not factor into a taxpayer’s application of the Pro-Rata Rule. Each non spousal inherited IRA has its own separate, hermetically sealed Pro-Rata Rule calculation. The inheriting beneficiary does a Pro-Rata Rule calculation on all IRAs he/she owns as the original owner, separate from any inherited IRAs. In addition, non spousal inherited IRAs cannot be rolled into a 401(k).

Mega Backdoor Roth

Good news: the concerns addressed in this blog post generally do not apply with respect to the Mega Backdoor Roth (sometimes referred to as a Mega Backdoor Roth IRA, though a Roth IRA does not necessarily have to be involved). Qualified plans such as 401(k)s are not subject to the Pro-Rata Rule. 

While 401(k)s are not subject to the Pro-Rata Rule, amounts within a particular 401(k) plan’s after-tax 401(k) are subject to the “cream-in-the-coffee” rule I previously wrote about here. Thus, if there is growth on Mega Backdoor Roth contributions before they are moved out of the after-tax 401(k), generally speaking either the taxpayer must pay income tax on the growth (if moved to a Roth account) or the taxpayer can separately roll the growth to a traditional IRA (which could then create a rather small Pro-Rata Rule issue with future Backdoor Roth IRAs). Fortunately, the cream-in-the-coffee rule has a much narrower reach than the Pro-Rata Rule.

Backdoor Roth IRA Tax Return Reporting

Watch me discuss Backdoor Roth IRA tax return reporting.

Conclusion

Get your IRAs in order so you can enjoy New Year’s Eve! 

December 31st is an important date when it comes to Backdoor Roth IRA planning. It is important to plan to have no (or at a minimum, very small) balances in traditional IRAs, SEP IRAs, and SIMPLE IRAs on December 31st when planning Backdoor Roth IRAs. 

None of what is discussed in this blog post is advice for any particular taxpayer. Those working through Backdoor Roth IRA planning issues are often well advised to reach out to professional advisors regarding their own tax situation.

Further Reading

I did a blog post about Backdoor Roth IRA tax return reporting here.

I did a deep dive on the taxation of Roth IRA withdrawals here.

I did a deep dive on the Pro-Rata Rule here.

FI Tax Guy can be your financial planner! Find out more by visiting mullaneyfinancial.com

Follow me on Twitter: @SeanMoneyandTax

This post is for entertainment and educational purposes only. It does not constitute accounting, financial, investment, legal, or tax advice. Please consult with your advisor(s) regarding your personal accounting, financial, investment, legal, and tax matters. Please also refer to the Disclaimer & Warning section found here.

Tax Deductions for Individuals

Tax deductions can be a confusing topic considering the many types of tax deductions and the terminology for them. Below I explain the different types of tax deductions you can claim on your tax return. You may be taking several of these types without even knowing it.

Types of Individual Tax Deductions

Exclusions

Many things we think of tax deductions are not treated as tax deductions on a tax return. Instead, they are excluded from taxable income. An exclusion from taxable income has the exact same effect as a tax deduction.

The most common exclusion is the exclusion for employer provided benefits, including health insurance, retirement plan contributions, and health savings accounts contributions. Here is an example:

Example: Mark has a salary of $100,000. He contributes ten percent ($10,000) of his salary to his employer’s 401(k) plan. His W-2 for the year will report wages of $90,000, not $100,000, and he will enter $90,000 as wages on his Form 1040. The $10,000 Mark contributed to his 401(k) is excluded from his gross income. This exclusion has the same income tax effect as a deduction.

Exclusions are a great form of deduction in that they are generally unlimited on your tax return, though they may have their own limitations. For example, in 2021 the most an employee under age 50 can exclude for contributions to a 401(k), 403(b), or a 457 is $19,500.

For those at least 70 1/2 years old, the qualified charitable distribution (“QCD”), which I wrote about here, can be a great tax planning technique. 

Exclusions also reduce adjusted gross income (“AGI”). Items that reduce AGI are great because AGI (or modified AGI, “MAGI”) is usually the measuring stick for whether a taxpayer qualifies for many tax benefits (such as eligibility for making a deductible contribution to an IRA or making a contribution to a Roth IRA). Lowering AGI is an important tax planning objective, since lower AGI opens the door to several tax benefits. 

Business Deductions

Business deductions include trade or business deductions generated from self-employment and investments in partnerships and rental property. On a Form 1040, these deductions are reported on Schedule C or Schedule E. Business deductions include salaries, rent, depreciation (deducting the cost of a business asset over a useful life), and other ordinary and necessary expenses.

Business deductions are generally great tax deductions because they are subject to relatively few limitations on your tax return. That said, limitations such as the passive activity loss rules and the at-risk limitations can limit a taxpayer’s ability to claim some business losses. Further, business deductions reduce not only income tax but also self-employment income, and thus, self-employment tax.

Business deductions are also valuable because they reduce AGI.

“For AGI” or “Above the Line” Deductions

On your Form 1040 you deduct certain expenses from your gross income to determine your AGI. Prior to tax returns filed for 2018 and later, these deductions were at the bottom of page 1 of the Form 1040. Starting with tax returns for 2018, these deductions are presented on Schedule 1 which accompanies Form 1040.

Examples of these deductions include one-half of self-employment tax paid by self-employed individuals, deductible contributions to IRAs, and contributions to certain self-employed retirement plans.  

Capital losses, generally up to $3,000 on any one tax return, can be deducted for computing AGI. Capital losses in excess of $3,000 are carried over to future tax years to be deducted against capital gains and against up to $3,000 per year of ordinary income. 

Health Savings Accounts (“HSAs”) are their own special breed. If contributions to an HSA are made through workplace payroll withholding, they are excluded from taxable income. If contributions to an HSA are made through another means (such as a check or wire transfer to the HSA), the contributions are for AGI deductions reported on Schedule 1. Which is better? From an income tax perspective, there is no difference. But from a payroll tax perspective, using payroll withholding is the clear winner. Amounts contributed to an HSA through payroll withholding are not subject to the FICA tax, creating another HSA tax win!

Standard Deduction or Itemized Deductions

Tax reform changed the landscape of itemized deductions. As a result of the tax reform bill enacted in December 2017, far fewer taxpayers will claim itemized deductions, and will instead claim the standard deduction.

The most common itemized deductions are state and local taxes (income, property, and in some cases, sales taxes), charitable contributions, and mortgage interest.

Taxpayers generally itemize if the sum total of itemized deductions (reported on Schedule A) exceed the standard deduction. Tax reform did two things to increase the chance that the standard deduction will exceed a taxpayer’s itemized deductions. First, the amount of the standard deduction increased. It went from $6,350 for single taxpayers in 2017 to $12,000 for single taxpayers in 2018. For married filing joint taxpayers, the standard deduction went from $12,700 in 2017 to $24,000 in 2018.

The standard deduction for 2021 is $12,550 (single) and $25,100 (MFJ) for most taxpayers. 

In addition, several itemized deductions were significantly reduced. For example, starting in 2018 there is a deduction cap of $10,000 per tax return ($5,000 for married filing separate tax returns) for state and local taxes. This hits married taxpayers particularly hard and increases the chance that if you are married filing joint you will claim the standard deduction, since you will need over $15,100 in other itemized deductions to itemize (using the 2021 numbers).

In addition, miscellaneous deductions, such as unreimbursed employee expenses and tax return preparation fees, were eliminated as part of tax reform.

Thus, many taxpayers will find that they will often claim the standard deduction. As discussed below, there will be planning opportunities for taxpayers to essentially push many itemized deductions (such as charitable contributions) into one particular tax year, itemize for that year, and then claim the standard deduction for the next several years.

Neither the standard deduction nor itemized deductions reduce AGI.

Special Deductions

In a relatively new development in tax law, there are now deductions that apply only after AGI has been determined and separate and apart from the standard deduction or itemized deductions. 

QBI Deduction

Tax reform created an entirely new tax deduction: the qualified business income deduction (also known as the QBI deduction or the Section 199A deduction). I have written about the QBI deduction here and here. Subject to certain limitations, taxpayers can claim, as a deduction, 20 percent of qualified business income, which is generally income from domestic business activities (not wage income), income from publicly-traded partnerships, and qualified REIT (real estate investment trust) dividends.

The QBI deduction does not reduce AGI.

Taxpayers can claim the QBI deduction regardless of whether they elect itemized deductions or the standard deduction.

Special Deduction for Charitable Contributions

For the 2021 tax year, taxpayers who do not claim itemized deductions are eligible for a special deduction for charitable contributions. The deduction is limited to $300 for single filers and $600 for MFJ filers.

As discussed by Jeffrey Levine, this deduction, like the QBI deduction, neither reduces AGI nor is an itemized deduction. 

The statutory language for this new deduction is found at Section 170(p). I believe that there is a very good chance that this deduction is extended to years beyond 2021, though as of now, it is only applicable to the 2021 tax year. 

Planning

Tax deductions provide a great opportunity for impactful tax planning. Here are some examples.

Timing

If your marginal income tax rate is the same every year, then you generally want to accelerate deductions. Thus, if you have a sole proprietorship and are a cash basis taxpayer, you are generally better off paying rent due on January 1, 2022 on December 31, 2021 instead of January 1, 2022 since the deduction saves the same amount of tax regardless of which tax year you pay it, but you’ll get the cash tax benefit sooner – on your 2021 income tax return instead of on your 2022 income tax return.

But there can be situations where you anticipate that your marginal tax rate will be greater next year than this year. In those cases, it makes sense to delay deductions. For example, perhaps you would make a large charitable contribution next year instead of before the end of the current year. Or, in the above example, you would pay the rent on January 1, 2022 to ensure the deduction is in 2022 instead of 2021.

Bunching

For some taxpayers, it may make sense to bunch deductions to maximize the total benefit of itemizing deductions versus claiming the standard deduction over several years. My favorite example of this is the donor advised fund. I’m not alone in my fondness of the donor advised fund. It allows you to contribute to a fund in one year, claim a charitable deduction for the entire amount of the contribution, and then donate from that fund to charities in subsequent years. The big advantage is that you get an enhanced upfront deduction in the first year and then claim the standard deduction in several subsequent years. This strategy only works if the amount of the deduction for the contribution to the donor advised fund is sufficient such that your itemized deductions in the year of the contribution exceed the standard deduction by a healthy amount.

Deadlines, Deadlines, Deadlines!!!

Different deductions have different deadlines. Many deductions have December 31st deadlines, so it is important to make the contribution by year-end. For charitable contributions, it is best to make the contribution online with a credit or debit card before January 1st if you are running really late, though if you place the contribution in a U.S. Postal Service mailbox prior to January 1st that counts as prior to the near year (though it makes it harder to prove you beat the deadline if you drop it in the mailbox on December 31st).

For employee contributions to a 401(k), the deadline is December 31st. Thus, if you are reading this on December 5th and you want to significantly increase your 401(k) contribution for 2021, you ought to get in touch with your payroll administrator and increase your contribution rate for your last paycheck ASAP.

By contrast, the deadline for a 2021 contribution to a deductible IRA or a non-payroll 2021 contribution to a HSA is April 15, 2022 (the date tax returns are due).

Self-employed retirement plans have their own sets of deadlines that should be considered.

Conclusion

Tax deductions present several important tax planning considerations. These considerations should include the taxpayer’s current marginal tax rate and future marginal tax rate. They should also include consideration of maximizing the combination of itemized deductions and the standard deduction over multiple taxable years.

FI Tax Guy can be your financial planner! Find out more by visiting mullaneyfinancial.com

Follow me on Twitter: @SeanMoneyandTax

This post is for entertainment and educational purposes only. It does not constitute accounting, financial, investment, legal, or tax advice. Please consult with your advisor(s) regarding your personal accounting, financial, investment, legal, and tax matters. Please also refer to the Disclaimer & Warning section found here.